Hollyn, the AI insurance broker for business
Confidential
Too complex for a form.
Too small for a broker’s full attention.
55–65% of broker staff time is adminest.
Vendor estimate. The account handler’s day goes on keying, chasing and re-formatting, not advice.
Renewals run late
They happen in a last-minute rush, not 90 days out, which leaves little time to shop the market.
In care, insurers are leaving
Insurers are exiting or restricting the sector; Hiscox exited care homes. Owners need someone to shop the market.
Premium axis is logarithmic. Sources: broker admin time is a vendor estimate (Softomate, 2026); Hiscox exit reported by Insurance Times. Full list in the appendix.
We sell the work, not software.
Agents run the whole renewal. A qualified broker approves every recommendation.
Client
Asks the owner for updated figures, chases late or partial replies, follows up when the risk changes.
Market selection
Picks 4–5 insurers from their care appetite and leaves out the ones that won’t write it.
Submissions
Builds a tailored submission for each insurer, pre-filled from public CQC data.
Questions and declines
Answers underwriters, pushes back on a poor quote, handles a decline or referral.
Recommendation
Compares terms and drafts the recommendation and demands-and-needs statement.
Broker approves
One screen of decisions. Approve or edit in a click, with an audit trail a network or the FCA can follow.
Paid like a broker: commission on placed policies (typically 10–20% of premium) plus a small fee, not a software licence.
The work just became automatable, and the market is moving.
Agents can run the job
Models can now run multi-party work that spans days: chasing, judgement calls, exceptions. Reading documents is already commodity.
The FCA is open to AI
No AI-specific rules: the existing ones apply. Its AI Live Testing programme is on its second cohort.
Consolidation leaves small accounts behind
Private equity is rolling up UK broking (Ardonagh, Clear, Brown & Brown). Their cost base is people and acquired books.
Insurers are retreating from care
Hiscox exited care homes. When capacity shrinks, owners need someone to shop the whole market.
Sources: FCA AI Live Testing second cohort (FinTech Futures); Insurance Times on care home capacity and Hiscox’s exit.
Proven in the US. Early in the UK.
UK: early. Meshed (FCA appointed representative, 51 insurers) automates the quote for SMEs generally. We go deep in care and run the whole job, renewals included.
Company figures from press and company materials, not independently verified. Map positions are our judgement.
£2bn a year in the UK. About £13bn with Western Europe and the US.
Method: businesses by size × premium per business × share placed by independent brokers × commission rate. Business counts are sourced (DBT, Eurostat, US Census); the other inputs are estimates. UK calibrated to GlobalData (£15.5bn SME premium, 2023), US to Conning ($158bn small commercial, 2025); Europe uncalibrated. Fees would add 10–20%. Tables in the appendix.
A care home renewal, run end to end.
- Kestlebury House, a fictional care home built from a real CQC listing, with its renewal 60 days out.
- Hollyn emails the owner, picks 5 underwriters and sends each a tailored submission.
- AI personas play the owner and underwriters, each with a hidden brief: questions, a poor quote, a decline on abuse cover. Nothing is scripted.
- The supervising broker, Alex Morgan, ACII (fictional, for the demo), only makes decisions, on one screen.
Broker minutes per renewal, against ~8–10 broker hours a year per care home todayest.

Independent care providers in England.
- Public data pre-fills the submission. CQC lists every location’s services, specialisms, website and inspection rating.
- The cover is specialist. Abuse, treatment risk, £10M employer’s liability: no quote-and-buy form handles it.
- Insurer exits create pain. Owners need someone to shop the market at renewal.
- Room to grow each account. The same owner also buys legal expenses and management liability cover.
Counts from the CQC locations file (7 October 2026), our own count by provider. Pool = locations × premium per location (est.) × commission of 15–20% (est.). Fees not included.
One broker, three times the accounts.
Pricing: no broker fee, and a better submission.
Commission flex only where it wins a switch. On the £10k home the client saves ~7%, and we keep ~£1,660 grossest.
All figures are estimates until we have real schedules. A home care agency: £4k premium, £850 gross, £635 net at AR stage, ~1 broker hour a year. Network share applies only while we trade as an appointed representative.
Trading in months, on a route the FCA knows.
A named senior manager is accountable for what the agents produce (SM&CR). Every approval is logged.
No AI-specific rules: ICOBS applies. The agent drafts the demands-and-needs statement; the broker approves.
Apply to the FCA’s AI Live Testing when the next cohort opens.
Buy a small authorised broker: permissions, agencies, a book and staff at once.
Our reading of the FCA Handbook (SUP 12, MIPRU, ICOBS), not legal advice. Median authorisation time for new firms, 2024/25: FCA service metrics. Details in the appendix.
Land with a free renewal health check.
A target list from public data
The CQC register joined to Companies House for directors and accounts, prioritised by renewal month.
The free health check
“Send us your schedule and we’ll show you what you’re not covered for, before your renewal.”
Take over the renewal
The owner signs a letter of appointment and we run the placement.
Cross-sell later
HR support, legal expenses and employment practices cover for the same owners.
Care associations
Care England, the Homecare Association, regional groups
Care accountants
Firms that already see the owner’s books
Care software
Rota and care-planning systems as referral partners
An owner-run care home (20–60 beds) or home care agency (30–150 staff), renewing in 3–6 months, rated Good or Requires Improvement, unhappy with last year’s increase.
Every step is a gate, and the first gates are people.
Document AI for finance, built through to an exit.
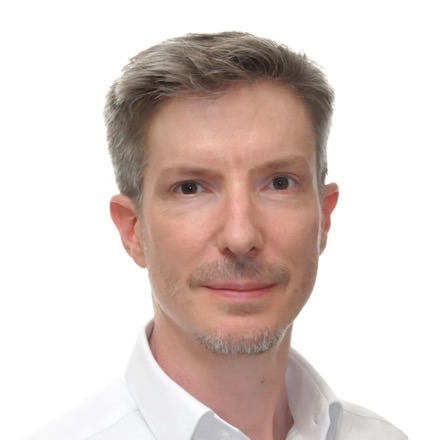
Phillip Mortimer
Machine learning engineer, CTO, quant and chartered accountant.
- Accelex · 2019–25CTO. Founding engineer and angel investor. Document AI for private-markets data: proof of concept to 60+ blue-chip clients, Seed to Series A, exit to Carta.
- Carta · 2025–26Senior Staff ML Engineer. Led the integration; built agentic document collection and extraction workflows.
- Dauphine · 2022–Visiting Lecturer in MLOps, LLMOps and AgentOps, Université Paris Dauphine – PSL.
- PwC, MS · 2001–16Chartered Accountant at PwC, then FX derivatives quant at Morgan Stanley, London and Tokyo (VP).
- EducationMSc Machine Learning, UCL (Distinction) · MPhys, Oxford (First) · FRM
A qualified commercial broker as co-founder
Cert/Dip CII, care or SME commercial experience. Wants to supervise agents rather than key data, and signs off every recommendation.
A 90-day gate: signed by week 8.
From a live demo to a regulated book of clients.
- PeopleA qualified broker co-founder, and the engineering to run the agents and the supervision desk.
- RegulationAn AR appointment, PII cover for an AI-led broker, and our own FCA application from month 6.
- ProductRenewal agents, the broker supervision desk with a full audit trail, and the free health check.
- MarketThe first care clients, through associations, care accountants and software partners.
a year, measured on live files, against 8–10 todayest.
by month 12, from the first 5 policies at day 90
of key fields right, with every escalation and approval logged
our own FCA permissions applied for by month 12
The detail behind the numbers.
What could break it, and what we do about it.
Insurer access
New brokers struggle to get insurer agencies. Mitigation: the network route brings its agencies, at the cost of a commission share.
A narrow care panel
Networks may lack abuse and treatment-risk capacity. Mitigation: decided in weeks 1–6; fallback niche is trades and construction.
Trust at claim time
Owners want a person when they claim. Mitigation: a named broker per account, with the agents doing the legwork.
PII for an AI-led broker
Cover may be hard to get for direct authorisation. Mitigation: tested early, a gate in weeks 6–10.
Incumbents and consolidators
They’ll add AI. Mitigation: their cost base is people and acquired books; ours is built around one broker supervising 600–800 accounts.
Premium per location is an estimate
It moves the niche size most. Mitigation: collect 10 real schedules in the first 90 days and re-run the numbers.
Harper coming to the UK
Harper could expand here. Mitigation: move quickly and own a niche and its insurer relationships. A reason to go faster, not to avoid the market.
Meshed is already trading
An FCA appointed representative with 51 insurer agreements; it could add care. Mitigation: go deep in care first (CQC-built submissions, care insurer appetite, renewals run end to end) and win the care channels early.
Sensitive data
Care claims histories hold residents’ health data (special category under UK GDPR). Mitigation: collect only what placement needs.
Businesses × premium × broker share × commission.
| Band | Businesses | Premium per business (est.) | Premium | Broker share (est.) | Broker-placed premium |
|---|---|---|---|---|---|
| No employees | 4.27M | £300 | £1.28bn | 50% | £0.64bn |
| 1–9 employees | 1.15M | £4,000 | £4.60bn | 65% | £2.99bn |
| 10–49 | 220k | £25,000 | £5.50bn | 85% | £4.68bn |
| 50–249 | 38k | £100,000 | £3.80bn | 90% | £3.42bn |
| Total | 5.68M | £15.2bn | 77% | £11.7bn |
£11.7bn × 17.5% = £2.05bn (£1.76bn at 15%, £2.35bn at 20%). Employer businesses only: £1.94bn.
GlobalData puts UK SME premium at £15.5bn (2023); the bottom-up lands within 2%. SME is 40% of the ~£38bn broker-placed commercial premium.
UK £2.0bn (£1.8–2.4bn) · W. Europe £2.6bn (£1.5–3.5bn; £5.4bn incl. tied agents) · US £8.7bn (£6.3–11.4bn). Total ~£13bn.
Business counts: DBT business population estimates 2025 (no-employee and 1–9 split from a secondary summary). Premium per business, broker share and commission are our estimates, set so the total matches GlobalData. Broker fees would add 10–20%.
Europe is the second £2–5bn. The US is the option.
| Country | SME premium €bn (est.) | Indep. broker share (est.) | Commission at 15% €bn |
|---|---|---|---|
| Germany | 17.0 | 35% | 0.89 |
| France | 11.0 | 35% | 0.58 |
| Italy | 8.2 | 25% | 0.31 |
| Spain | 6.4 | 30% | 0.29 |
| Netherlands | 4.6 | 60% | 0.41 |
| Belgium | 2.1 | 60% | 0.19 |
| Austria | 2.0 | 50% | 0.15 |
| Ireland | 1.7 | 75% | 0.19 |
| Total | 52.9 | 38% | 3.0 (£2.6bn) |
Lower premium per business than the UK (accidents at work are state-insured in Germany, France, Austria and Belgium) and a smaller independent broker share. Not calibrated: no published SME total found.
| US band | Firms | Premium per firm (est.) | Premium |
|---|---|---|---|
| No employees | ~29M (est.) | $400 | $11.6bn |
| 1–9 employees | 5.06M | $10,000 | $50.6bn |
| 10–49 | 1.08M | $55,000 | $59.7bn |
| 50–249 | ~0.20M | $150,000 | $30.4bn |
| Total | $152bn |
Conning puts US small commercial at $158bn (2025); within 4%. Independent agents place ~55% (est.) at 13.5% (est.): $11.3bn, about £8.7bn at $1.30. Licensing is state by state, and Harper is already there.
Eurostat sbs_sc_ovw 2023 (enterprises by size class; 30% of 0–9 firms assumed to have staff); US Census SUSB 2022. € at 1.17 to the £; $ at 1.30 (est.). Europe range £1.5–3.5bn; including tied agents’ share ~£5.4bn. Nordics and Switzerland excluded (would add ~15%).
From the CQC register to a commission pool.
| CQC register, 7 Oct 2026 | Locations | Providers |
|---|---|---|
| Care homes | 14,917 | 7,218 |
| Home care agencies | 14,235 | 11,070 |
| All care providers | 29,152 | 17,719 |
| Providers with 1 location | 14,684 | |
| Providers with 2–5 locations | 2,540 | |
| Target: ≤5 locations | 21,261 | 17,224 |
| Excluded: 6+ locations | 7,891 | 495 |
Target locations: 8,954 care homes and 12,307 home care agencies.
| Input | Low | Central | High |
|---|---|---|---|
| Premium per care home, all lines (est.) | £6k | £10k | £15k |
| Premium per home care agency (est.) | £2.5k | £4k | £6k |
| Premium pool | £84M | £139M | £208M |
| Commission rate (est.) | 15% | 17.5% | 20% |
| Commission pool | £13M | £24M | £42M |
One insurer quotes £1.5–6k for care homes, which we read as small residential homes; nursing, dementia, property sums and abuse cover push it up. A start-up home care agency pays ~£1–3k. 5% of the niche is ~£1.2M of commission; at 12.5% commission and no fees the pool falls to ~£16M.
CQC locations file (Using CQC data), our own count by provider. Premium references: Simply Quote, Policybee, Birdie, Gallagher. Fees excluded; broker fees would add 10–20%.
Pass on the cost advantage where it costs us least.
| Per client a year (est.) | Care home | Home care |
|---|---|---|
| Premium | £10,000 | £4,000 |
| Commission at 17.5% | £1,750 | £700 |
| Broker fee | £250 | £150 |
| Gross revenue | £2,000 | £850 |
| Network share, 25% (AR only) | –£500 | –£215 |
| Net revenue, AR stage | £1,500 | £635 |
| Broker hours, traditional | 8–10 | 4–6 |
| Broker hours, target | 1.5–2 | ~1 |
| Lever, on the £10k care home | Client pays | Saving | Our gross |
|---|---|---|---|
| Typical broker: 17.5% + £250 fee | £10,250 | – | £2,000 |
| 1. No broker fee | £10,000 | 2.4% | £1,750 |
| 2. No fee + a better submission (5% lower net premium) | £9,500 | 7.3% | £1,663 |
| 3. 12.5% commission, no fee | £9,429 | 8.0% | £1,179 |
| 3. 10% commission, no fee | £9,167 | 10.6% | £917 |
Gross premium = net premium ÷ (1 − commission rate); the insurer nets £8,250. Levers 1 and 2 on every account; lever 3 only where it wins a switch: larger accounts, multi-site groups, a reference client. Longer term: net premium plus a flat fee.
All estimates. At ~2 broker hours a client, one qualified broker supervises ~600–800 accounts against ~200–300 for a traditional account handler.
Three routes, in sequence.
Appointed representative of a network
The network is authorised and takes regulatory responsibility (SUP 12). Gives permissions, PII, insurer agencies, e-trading, compliance monitoring. ~2–3 months to trade (est.); the principal notifies the FCA 30+ days before. Network keeps 20–30% (est.; terms unpublished). We must own the client book.
Our own permissions
Arranging and advising on non-investment insurance; assisting in claims. SM&CR core firm. Capital: higher of £5,000 or 2.5% of distribution income (our reading). PII: €1,300,380 per claim, aggregate the higher of €1,924,560 or 10% of income. No client money at first (risk transfer agreements). Median 112 days; plan for 6 months. ~£100–200k for year one (est.).
Buy a small authorised broker
Many owner-run brokers are near retirement. Brings permissions, agencies, a book and qualified staff. The FCA approves the change in control: a statutory 60 working-day assessment. Best once the agents are proven on AR files.
How the agents fit the rules. No AI-specific rules; existing ones apply. A named senior manager is accountable. Every sale needs a demands-and-needs statement (ICOBS 5); the agent drafts, the broker approves. Care providers are business customers, so most of the Consumer Duty doesn’t apply, but small businesses can still go to the Financial Ombudsman. Residents’ health data in claims histories is special category data under UK GDPR.
Our reading of the FCA Handbook (SUP 12, MIPRU 3.2 and 4.2, ICOBS 5, PS22/11, FSMA s189), not legal advice. Sources in A7.
Where the numbers come from.
Care and the CQC
- CQC: Using CQC data (locations file, 7 Oct 2026; counts are ours)
- Insurance Times: care home capacity and Hiscox’s exit
- Simply Quote: care home insurance · Policybee: domiciliary care
- Birdie: starting a home care agency · Gallagher: care home insurance
Regulation
- FCA MIPRU 3.2: PII · FCA 2021/30 PII limits · SUP 12: appointed representatives
- FCA authorisations service metrics
- Insurance Age: insurance authorisations missed target
- FinTech Futures: FCA AI Live Testing second cohort
Market size
- DBT business population estimates 2025
- GlobalData: UK SME insurance, £15.52bn (2023)
- Eurostat sbs_sc_ovw, 2023 · US Census SUSB 2022
- Conning via Risk & Insurance: US small commercial $158bn
Competitors and the broker market
Company figures come from press and company materials and have not been independently verified. Regulatory points are our reading of the FCA Handbook, not legal advice.